
 Listen to this article
Can the Bajaj Life Supreme Horizon Plan truly help you build substantial long-term wealth, or do its charges and conditions limit its potential?
Does the Bajaj Life Supreme Horizon Plan offer the right balance between market-linked growth and life protection, or are there better alternatives available?
Is the Bajaj Life Supreme Horizon Plan a smart investment for your future goals, or would separating insurance and investment provide greater flexibility?
In this review, we examine its features, charges, potential returns, and limitations, with illustrative examples to assess whether the plan is suitable for long-term wealth creation.
What are the plan options in the Bajaj Life Supreme?
Bajaj Life Supreme is available in nine different variants, each designed with different features and benefits:
- Advantage
- Builder
- Classic
- Diamond
- Elite
- Fortune
- Gold
- Horizon
- Inspire
This article focuses on the Bajaj Life Supreme – Horizon variant. The plan’s features, benefits, costs, and potential returns will be examined to assess whether it offers a suitable combination of insurance protection and investment for long-term financial planning.
Table of Contents:
What is the Bajaj Life Supreme Horizon?
What are the features of the Bajaj Life Supreme Horizon?
Who is eligible for the Bajaj Life Supreme Horizon?
What are the benefits of the Bajaj Life Supreme Horizon?
What are the investment strategies and fund options of the Bajaj Life Supreme Horizon?
What are the charges of the Bajaj Life Supreme Horizon?
Grace Period, Discontinuance and Revival of Bajaj Life Supreme Horizon
Free Look Period for the Bajaj Life Supreme Horizon
Surrendering the Bajaj Life Supreme Horizon
What are the advantages of the Bajaj Life Supreme Horizon?
What are the disadvantages of the Bajaj Life Supreme Horizon?
Research Methodology of Bajaj Life Supreme Horizon
Benefit Illustration – IRR Analysis of Bajaj Life Supreme Horizon
Bajaj Life Supreme Horizon Vs. Other Investments
Bajaj Life Supreme Horizon Vs. Pure-Term + Mutual Fund
Final Verdict on the Bajaj Life Supreme Horizon
What is the Bajaj Life Supreme Horizon?
Bajaj Life Supreme – Horizon is a Unit Linked Non-Participating Individual Life Savings Insurance Plan.
It blends the power of life cover with market-linked returns. This ULIP allows you to plan for any of your long-term goals. This all-in-one plan helps you to grow your wealth while financially securing your loved ones.
What are the features of the Bajaj Life Supreme Horizon?
- Market-Linked Return Potential: Opportunity to earn market-linked returns through investments linked to the chosen funds.
- Return of Premium Allocation Charges: Premium allocation charges are returned with a stated 7% p.a. guaranteed compounding benefit, subject to the policy terms.
- Return of Mortality Charges: Mortality charges deducted during the policy term are returned, subject to the applicable conditions.
- Loyalty Additions from the 16th Policy Year: Loyalty additions are credited from the 16th policy year, providing an additional benefit for long-term policyholders.
- Systematic Partial Withdrawals: Allows systematic partial withdrawals from the fund value, which can be used to create a regular source of income.
- Fund Switching: Provides the flexibility to switch between available investment funds without a separate switching tax event, subject to policy terms and applicable tax rules.
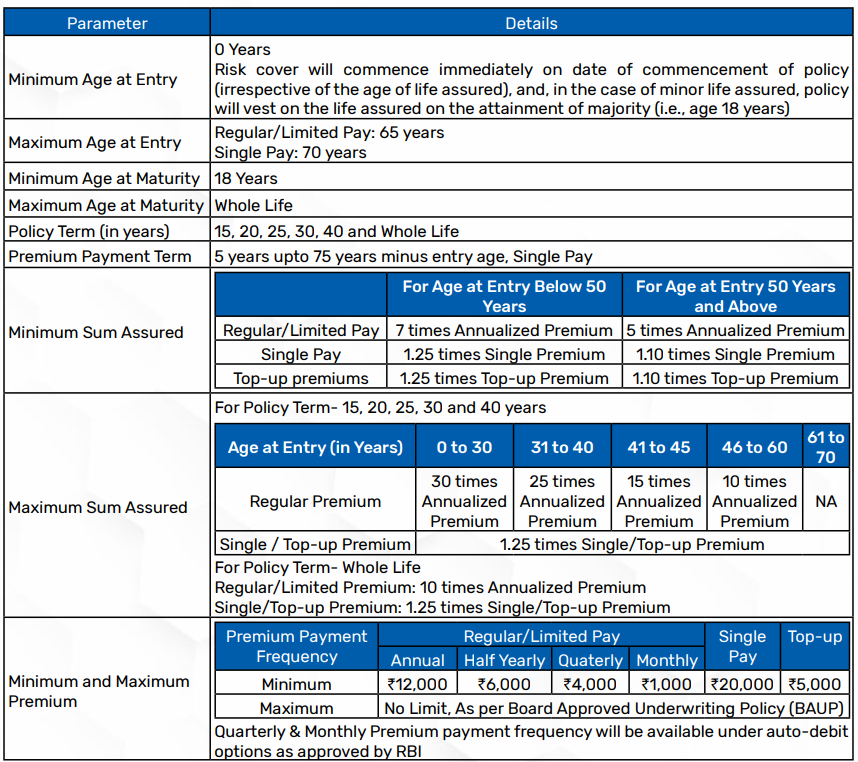
Who is eligible for the Bajaj Life Supreme Horizon?
What are the benefits of the Bajaj Life Supreme Horizon?
1. Maturity Benefit
Fund Value shall be payable to you on the Maturity Date, provided the life assured (person whose life is covered under the policy) is alive.
You will have an option to receive the Maturity Benefit as a lump sum or as a systematic payout for a maximum of five years under the Settlement Option.
2. Death Benefit
In case of unfortunate death of the Life Assured during the Bajaj Life Supreme Horizon Plan Policy term, provided all due premiums have been paid, and the policy is in force, the Death Benefit payable will be the higher of:
- Prevailing Sum Assured, including top-up sum assured, if any
- Fund Value as available on date of intimation of death
- Guaranteed Death Benefit i.e.105% of Total Premiums Paid till the date of death, including top-up premium
The policy will terminate on the date of intimation of death of the life assured. Benefits available under the Plan
3. Additions to the Fund
Guaranteed Wealth Booster
Premium Allocation Charges deducted during the Bajaj Life Supreme Horizon Plan policy term are accumulated at a guaranteed rate of 7% per year (compounded annually) and will be added to your fund value at the end of the 15th policy year.
Loyalty Additions
At the end of every year from the 16th policy year till the end of the Bajaj Life Supreme Horizon Plan policy term, additional units will be added to your fund value as Loyalty Additions
Return of Mortality Charge (ROMC)
Life cover charges deducted during the Bajaj Life Supreme Horizon Plan policy term shall be added back to your fund value as per the table given below
| Additions to the Fund | Return of Mortality Charge1 |
| 15th Policy Year | 100% of the Mortality Charge1 deducted till 15th year |
| Every 5th Policy year after the 15th policy year and before maturity | 100% of Mortality Charges1 deducted in the last 5 policy years |
| At Maturity | 100% of the Mortality Charges1 deducted minus mortality charges already returned |
What are the investment strategies and fund options of the Bajaj Life Supreme Horizon?
A. Investor-selectable Portfolio Strategy:
If you want to allocate your Premiums based on your personal choice and decision, you can opt for this Investment Strategy and choose from among the 21 Funds below to suit your investment needs.
| Asset Allocation | |||||
| S no | Fund Name | Equity | Debt | Money Market | Risk profile |
| 1 | Nifty 500 Low Volatility 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 2 | Opportunities Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 3 | BSE 500 Quality 50 Index Fund3 | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 4 | BSE 500 Dividend Leaders 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 5 | India Consumption Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 6 | Pure Stock Innovation | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 7 | BSE 500 Enhanced Value 50 Index Fund3 | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 8 | Equity Growth Fund II | Not less than 60% | 0% – 40% | 0% – 40% | Very High |
| 9 | Accelerator Mid-Cap Fund II | Not less than 60% (at least 50% in Mid cap) | 0% – 40% | 0% – 40% | Very High |
| 10 | Pure Stock Fund | Not less than 60% | 0% – 40% | 0% – 40% | Very High |
| 11 | Pure Stock Fund II | Not less than 75% | — | 0% -25% | Very High |
| 12 | Flexi Cap Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 13 | Sustainable Equity Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 14 | Small Cap Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 15 | Midcap Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 16 | SmallCap Quality Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 17 | Nifty Alpha 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 18 | Nifty 200 Alpha 30 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 19 | Nifty 200 Momentum 30 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 20 | Nifty 500 Multicap Momentum Quality 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 21 | Focused 25 Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 22 | Nifty 500 Multifactor 50 Index Fund | 65% – 100% | 0% – 35% | 0% – 35% | Very High |
| 23 | Asset Allocation Fund II | 40% – 90% | 0% – 60% | 0% – 50% | High |
| 24 | Blue-chip Equity Fund | Not less than 60% | 0% – 40% | 0% – 40% | High |
| 25 | Dynamic Asset Allocation Fund | 10% 90% | 10% 90% | 0% – 80% | High |
| 26 | Bond Fund | — | 40% – 100% | 0% – 60% | Moderate |
| 27 | Individual Short-Term Debt Fund | — | 40% – 100% | 0% – 60% | Moderate |
| 28 | Debt Plus Fund | Not less than 80% | 0%-20% | 0%-20% | Moderate |
| 29 | Liquid Fund | — | — | 100% | Low |
B. Wheel of Life Portfolio Strategy – II:
In this Portfolio Strategy, at the commencement of the Bajaj Allianz Long-Life Goal III Plan Policy, the Regular/Limited Premium and the Top-up Premium, if any, would be allocated in the Funds mentioned (namely Equity Growth Fund II, Accelerator Mid-Cap Fund II, Bond Fund & Liquid Fund) in the proportion as mentioned in the table below, depending on the outstanding years to maturity.
| Proportion in Following Funds | |||||
| Years to Maturity | Equity Growth Fund II | Accelerator Mid-Cap Fund II | Bond Fund | Liquid Fund | Total |
| 10 & above | 40% | 45% | 15% | 0% | 100% |
| 9 | 35% | 50% | 15% | 0% | 100% |
| 8 | 30% | 55% | 15% | 0% | 100% |
| 7 | 25% | 60% | 15% | 0% | 100% |
| 6 | 25% | 60% | 15% | 0% | 100% |
| 5 | 20% | 65% | 15% | 0% | 100% |
| 4 | 20% | 55% | 15% | 10% | 100% |
| 3 | 20% | 50% | 15% | 15% | 100% |
| 2 | 10% | 30% | 30% | 30% | 100% |
| 1 | 0% | 0% | 35% | 65% | 100% |
C. Trigger-Based Portfolio Strategy:
Under this Portfolio Strategy, Regular/Limited Premiums and Top-up Premiums, if any, will be allocated between two Funds, Equity Growth Fund II (an equity-oriented Fund) and Bond Fund (a debt-oriented Fund), in a 75%: 25% proportion.
The Fund value proportions may subsequently get altered due to market movements.
Any appreciation over three times the value of units is considered a gain and is switched to the Liquid Fund.
Later, it will be switched to the Equity Growth Fund II and the Bond Fund such that, after the transfer, the ratio of the value of units in the Equity Growth Fund II to that in the Bond Fund is restored to 75%:25%.
D. Auto Transfer Portfolio Strategy:
This strategy helps you to invest your money systematically by automatically transferring your money every month, from a low-risk Fund to the Fund(s) of your choice.
In this Portfolio Strategy, your Premium will be allocated to the Bond Fund and/or Liquid Fund, as specified by you.
At the start of each monthly anniversary of the Bajaj Allianz Long-Life Goal III Plan Policy, a proportion (as mentioned below) of the Fund value in the Bond Fund and/or Liquid Fund as on that date will be switched to the other Fund/s (available in the plan) as specified by you.
The proportion of Fund value = 1/ Outstanding no. of months till the next premium due date.
E. Capital Preservation – Orientation Strategy
You can opt for this strategy at the inception of the Policy if the Policy term is at least 10 years, and the minimum difference between the Bajaj Life Supreme Horizon Plan Policy term and Premium payment term is at least 5 years.
The objective of the strategy is to optimise risk and return by investing across five predetermined Funds, which are a mix of very high to low-risk Funds, in such a way that the monies invested over the years, along with the accumulated returns, are subjected to lesser market volatility in the years closer to maturity.
At each policy anniversary, the Company will reallocate the Fund Value among various funds in the proportion based on the table below, depending on the outstanding years to maturity.
| Proportion in the Following Funds | ||||||
| Years to Maturity | Equity Growth Fund II | Accelerator Mid-Cap Fund II | Pure-Stock Fund II | Bond Fund | Liquid Fund | Total |
| 10 & above | 40% | 15% | 15% | 30% | 0% | 100% |
| 9 | 35% | 15% | 15% | 35% | 0% | 100% |
| 8 | 30% | 15% | 15% | 40% | 0% | 100% |
| 7 | 30% | 15% | 15% | 40% | 0% | 100% |
| 6 | 30% | 10% | 15% | 45% | 0% | 100% |
| 5 | 25% | 10% | 15% | 40% | 10% | 100% |
| 4 | 20% | 5% | 10% | 40% | 25% | 100% |
| 3 | 15% | 0% | 5% | 40% | 40% | 100% |
| 2 | 0% | 0% | 0% | 40% | 60% | 100% |
| 1 | 0% | 0% | 0% | 0% | 100% | 100% |
What are the charges of the Bajaj Life Supreme Horizon?
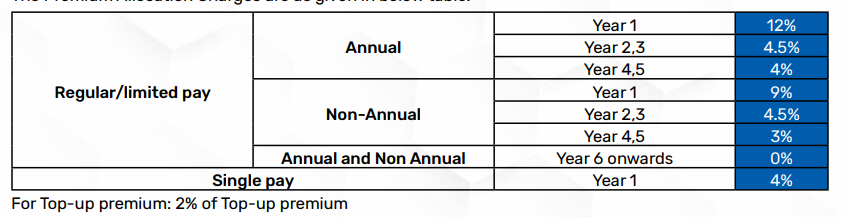
i. Premium Allocation Charge
A certain percentage of each premium paid by you will be deducted as Premium Allocation Charge, and the remaining amount will be invested at the prevailing unit price.
ii. Policy Administration Charge
| Mode | As % of Annualized/Single Premium | ||
| 1st to 5th Year | 6th Year to 20th Year | 21st Year onwards | |
| Regular/Limited Pay | 0.09% | 0.20% | Nil |
| Single Pay | 0.05% | Nil | |
iii. Fund Management Charge
| Fund | Fund Management Charge per annum |
| Nifty 500 Low Volatility 50 Index Fund | 1.35% |
| Opportunities Fund | 1.35% |
| BSE 500 Quality 50 Index Fund | 1.35% |
| BSE 500 Dividend Leaders 50 Index Fund | 1.35% |
| India Consumption Fund | 1.35% |
| Pure Stock Innovation Fund | 1.35% |
| BSE 500 Enhanced Value 50 Index Fund | 1.35% |
| Equity Growth Fund II | 1.35% |
| Accelerator Mid Cap Fund II | 1.35% |
| Pure Stock Fund | 1.35% |
| Flexi Cap Fund | 1.35% |
| Sustainable Equity Fund | 1.35% |
| Dynamic Asset Allocation Fund | 1.35% |
| Small Cap Fund | 1.35% |
| Midcap Index Fund | 1.35% |
| SmallCap Quality Index Fund | 1.35% |
| Nifty Alpha 50 Index Fund | 1.35% |
| Nifty 200 Alpha 30 Index Fund | 1.35% |
| Nifty 200 Momentum 30 Index Fund | 1.35% |
| Nifty 500 Multicap Momentum Quality 50 Index Fund | 1.35% |
| Nifty 500 Multifactor 50 Index Fund | 1.35% |
| Focused 25 Fund | 1.35% |
| Pure Stock Fund II | 1.30% |
| Asset Allocation Fund II | 1.25% |
| Bluechip Equity Fund | 1.25% |
| Liquid Fund | 0.95% |
| Bond Fund | 0.95% |
| Individual Short Term Debt Fund | 0.95% |
| Debt Plus Fund | 0.70% |
| Discontinued Life Policy Fund | 0.50% |
iv. Mortality Charge
Mortality Charge is the cost of the life insurance cover which depends on your age, gender, chosen sum assured and Board Approved Underwriting Policy (BAUP).
Mortality Charge will be deducted at each monthly anniversary by cancellation of units at the prevailing unit price.
v. Miscellaneous Charge
The miscellaneous charge will be charged at the rate of ₹100/- per transaction (as mentioned in the respective section). This charge will be deducted upon cancellation of Units.
vi. Discontinuance / Surrender Charge
Under a Regular/Limited Premium Policy, the Discontinuance Charge shall apply to the Regular Premium Fund Value based on the year of discontinuance and premium amount.
Inference from the charges: ULIPs can involve several charges that are generally not present in the same form in other market-linked investments, such as premium allocation charges, policy administration charges, and discontinuance charges. These costs reduce the amount available for investment or are deducted from the policy value, which can drag down returns over the long term. Therefore, when evaluating a ULIP, it is important to look beyond the stated market-linked returns and assess the impact of all charges on the actual returns received by the investor.
Grace Period, Discontinuance and Revival of Bajaj Life Supreme Horizon
Grace Period
The grace period for payment of premium is 15 days for monthly mode of premium payment and 30 days for other modes of premium payment commencing from the premium due date.
Discontinuance
On Discontinuance of Regular/limited Premiums due during the first five Policy years, the Policy will be converted to a Discontinued Life Policy.
The Regular Premium Fund value less the Discontinuance/Surrender charge, along with the Top-up Premium Fund value, will be transferred to the Discontinued Life Policy Fund.
You can receive the Discontinued value (as Surrender Value) at the end of the lock-in period of five Policy years or the date of surrender, whichever is later.
On discontinuance of the due Regular/limited Premiums after the lock-in period of five Policy years, the Bajaj Life Supreme Horizon Plan Policy will be, immediately & automatically, converted to a Paid-up Policy, with risk cover under the base Policy reduced to the extent of the Paid-up Sum Assured and without any Loyalty Additions, Guaranteed Wealth Booster, ROMC or Rider cover.
Revival
A Discontinued Policy can only be revived within three (3) years from the date of first unpaid premium.
Free Look Period for the Bajaj Life Supreme Horizon
You have a free look period of 30 days beginning from the date of receipt of the policy document, whether received electronically or otherwise, to review the terms and conditions of such policy, except for those policies with tenure of less than a year.
In the event you disagree with any of the Bajaj Life Supreme Horizon Plan policy terms or conditions, or otherwise and have not made any claim, you shall have the option to return the policy to the insurer for cancellation
Surrendering the Bajaj Life Supreme Horizon
On Surrender during the lock-in period of 5 years, the Fund Value, after deducting the applicable discontinuance/surrender charge, if any, as on the date of surrender, will be transferred to the Discontinued Life Policy Fund, and all risk and rider cover shall cease immediately.
The discontinuance value as at the end of the lock-in period will be available to you as surrender benefit. The fund management charges of the Discontinued Life Policy Fund will be applicable during this period, and no other charges will be applied.
On Surrender after the lock-in period of 5 years, the Fund Value, as on the date of surrender, will be paid as Surrender Value. The Policy shall terminate upon payment of the full surrender value.
What are the advantages of the Bajaj Life Supreme Horizon?
- Partial Withdrawal: Allows policyholders to access a portion of the accumulated fund value to meet immediate financial requirements, subject to applicable conditions.
- Systematic Partial Withdrawal: Provides the option to withdraw a predetermined percentage of the fund value at regular intervals, offering structured liquidity from the policy.
- Top-up Premiums: Allows policyholders to invest additional amounts through Top-up premiums, subject to the terms and conditions of the policy.
- Fund Switching: Under the Investor Selectable Portfolio Strategy, policyholders can switch between available funds to modify their investment allocation.
- Change in Premium Paying Term: The Premium Paying Term (PPT) can be changed after completion of the first five policy years, subject to the applicable terms.
- Reduction in Premium: Regular or limited premiums can be reduced after completion of five policy years, subject to the policy conditions.
- Change in Policy Features: Policyholders may have the option to reduce the Sum Assured, increase the policy term, or change the premium payment frequency, as permitted under the plan.
- Maturity Benefit in Instalments: The maturity benefit can be received in instalments under the Settlement Option instead of as a single lump-sum payment, subject to the applicable terms.
What are the disadvantages of the Bajaj Life Supreme Horizon?
- No Policy Loan: The plan does not provide a policy loan facility, limiting access to the policy’s value during financial emergencies.
- Five-Year Lock-in: The policy has a five-year lock-in period, during which withdrawals or exit options are restricted as per the policy terms.
- Only Net Premium Is Invested: The premium is subject to applicable charges before being allocated to the investment funds. Therefore, the entire premium does not get invested from the outset.
- Insufficient Life Cover: The life cover offered may not be adequate to meet the policyholder’s actual protection needs. In addition, a Whole Life cover may not be necessary for most financial planning requirements.
- Delayed Return of Charges: Although certain charges are returned to the policy corpus at a later stage, the amount remains unavailable for investment during the intervening period. As a result, the potential for compounding on those amounts is lost.
Research Methodology of Bajaj Life Supreme Horizon
This section examines the potential returns from the Bajaj Life Supreme Horizon Plan. Since the plan invests in market-linked funds, the investor takes on investment risk.
The key question is whether the returns generated after accounting for the plan’s costs are adequate for the level of risk undertaken. The benefit illustration in the policy brochure provides a useful basis for this analysis.
Benefit Illustration – IRR Analysis of Bajaj Life Supreme Horizon
Consider a 40-year-old male opting for a Sum Assured of ₹50 lakh. The Policy Term is 60 years, with a Premium Paying Term of 10 years and an Annual Premium of ₹5 lakh.
The fund value at the end of the Bajaj Life Supreme Horizon Plan policy term is payable as the maturity benefit.
| Male | 40 years |
| Sum Assured | ₹ 50,00,000 |
| Policy Term | Whole Life |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 5,00,000 |
The benefit illustration assumes Projected Investment Rates of Return (PIRR) of 4% p.a. and 8% p.a. These are only illustrative assumptions and are not guaranteed.
The actual fund value will depend on market performance, fund performance, and the charges applicable to the policy.
| At 4% p.a. | At 8% p.a. | ||||
| Age | Year | Annualised premium / Maturity benefit | Death benefit | Annualised premium / Maturity benefit | Death benefit |
| 40 | 1 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 41 | 2 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 42 | 3 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 43 | 4 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 44 | 5 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 45 | 6 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 46 | 7 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 47 | 8 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 48 | 9 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 49 | 10 | -5,00,000 | 50,00,000 | -5,00,000 | 50,00,000 |
| 50 | 11 | 0 | 50,00,000 | 0 | 50,00,000 |
| 51 | 12 | 0 | 50,00,000 | 0 | 50,00,000 |
| 52 | 13 | 0 | 50,00,000 | 0 | 50,00,000 |
| 53 | 14 | 0 | 50,00,000 | 0 | 50,00,000 |
| 54 | 15 | 0 | 50,00,000 | 0 | 50,00,000 |
| 55 | 16 | 0 | 50,00,000 | 0 | 50,00,000 |
| 56 | 17 | 0 | 50,00,000 | 0 | 50,00,000 |
| 57 | 18 | 0 | 50,00,000 | 0 | 50,00,000 |
| 58 | 19 | 0 | 50,00,000 | 0 | 50,00,000 |
| 59 | 20 | 0 | 50,00,000 | 0 | 50,00,000 |
| 60 | 21 | 0 | 50,00,000 | 0 | 50,00,000 |
| 61 | 22 | 0 | 50,00,000 | 0 | 50,00,000 |
| 62 | 23 | 0 | 50,00,000 | 0 | 50,00,000 |
| 63 | 24 | 0 | 50,00,000 | 0 | 50,00,000 |
| 64 | 25 | 0 | 50,00,000 | 0 | 50,00,000 |
| 65 | 26 | 0 | 50,00,000 | 0 | 50,00,000 |
| 66 | 27 | 0 | 50,00,000 | 0 | 50,00,000 |
| 67 | 28 | 0 | 50,00,000 | 0 | 50,00,000 |
| 68 | 29 | 0 | 50,00,000 | 0 | 50,00,000 |
| 69 | 30 | 0 | 50,00,000 | 0 | 50,00,000 |
| 70 | 31 | 0 | 50,00,000 | 0 | 50,00,000 |
| 71 | 32 | 0 | 50,00,000 | 0 | 50,00,000 |
| 72 | 33 | 0 | 50,00,000 | 0 | 50,00,000 |
| 73 | 34 | 0 | 50,00,000 | 0 | 50,00,000 |
| 74 | 35 | 0 | 50,00,000 | 0 | 50,00,000 |
| 75 | 36 | 0 | 50,00,000 | 0 | 50,00,000 |
| 76 | 37 | 0 | 50,00,000 | 0 | 50,00,000 |
| 77 | 38 | 0 | 50,00,000 | 0 | 50,00,000 |
| 78 | 39 | 0 | 50,00,000 | 0 | 50,00,000 |
| 79 | 40 | 0 | 50,00,000 | 0 | 50,00,000 |
| 80 | 41 | 0 | 50,00,000 | 0 | 50,00,000 |
| 81 | 42 | 0 | 50,00,000 | 0 | 50,00,000 |
| 82 | 43 | 0 | 50,00,000 | 0 | 50,00,000 |
| 83 | 44 | 0 | 50,00,000 | 0 | 50,00,000 |
| 84 | 45 | 0 | 50,00,000 | 0 | 50,00,000 |
| 85 | 46 | 0 | 50,00,000 | 0 | 50,00,000 |
| 86 | 47 | 0 | 50,00,000 | 0 | 50,00,000 |
| 87 | 48 | 0 | 50,00,000 | 0 | 50,00,000 |
| 88 | 49 | 0 | 50,00,000 | 0 | 50,00,000 |
| 89 | 50 | 0 | 50,00,000 | 0 | 50,00,000 |
| 90 | 51 | 0 | 50,00,000 | 0 | 50,00,000 |
| 91 | 52 | 0 | 50,00,000 | 0 | 50,00,000 |
| 92 | 53 | 0 | 50,00,000 | 0 | 50,00,000 |
| 93 | 54 | 0 | 50,00,000 | 0 | 50,00,000 |
| 94 | 55 | 0 | 50,00,000 | 0 | 50,00,000 |
| 95 | 56 | 0 | 50,00,000 | 0 | 50,00,000 |
| 96 | 57 | 0 | 50,00,000 | 0 | 50,00,000 |
| 97 | 58 | 0 | 50,00,000 | 0 | 50,00,000 |
| 98 | 59 | 0 | 50,00,000 | 0 | 50,00,000 |
| 99 | 60 | 0 | 50,00,000 | 0 | 50,00,000 |
| 2,39,49,552 | 19,20,18,659 | ||||
| IRR | 2.86% | 6.76% | |||
At a 4% p.a. assumed investment return, the projected fund value is ₹2.39 crore, resulting in an IRR of approximately 2.86% as per the Bajaj Life Supreme Horizon Plan maturity calculator.
The significant difference between the assumed fund return and the investor’s IRR highlights the impact of the policy’s costs and deductions over the long term.
At an 8% p.a. assumed investment return, the projected fund value is ₹19.20 crore, translating into an IRR of approximately 6.76% as per the Bajaj Life Supreme Horizon Plan maturity calculator.
Even with the higher assumed market return, the investor’s actual return remains substantially lower after accounting for the policy structure and associated costs.
These figures highlight an important point: market-linked does not necessarily mean market-level returns for the investor.
The fund may earn the assumed rate, but the return ultimately received by the policyholder is affected by the various charges and deductions under the plan.
For a 60-year policy horizon, the difference between the assumed investment return and the investor’s actual IRR becomes particularly significant because of the effect of compounding.
Investors should therefore evaluate the plan based on the net IRR, rather than focusing only on the projected fund value.
The plan also comes with long-term liquidity considerations, while the Sum Assured of ₹50 lakh may be inadequate for meaningful life protection depending on the policyholder’s financial responsibilities.
Based on the illustrated returns, costs, liquidity considerations, and level of life cover, the Bajaj Life Supreme Horizon warrants careful evaluation before being considered for long-term wealth creation.
Bajaj Life Supreme Horizon Vs. Other Investments
Market-linked alternatives such as equity mutual funds can provide greater flexibility and return potential than a ULIP.
To understand the difference, let’s compare the Bajaj Life Supreme Horizon Plan with a separate combination of term insurance and mutual fund investment, using the same parameters as the earlier illustration.
Instead of combining insurance and investment in a single product, the two objectives can be considered separately. This makes the cost of insurance and the amount available for investment more transparent.
Bajaj Life Supreme Horizon Vs. Pure-Term + Mutual Fund
Life Cover: A pure term insurance policy providing ₹50 lakh of life cover would cost approximately ₹26,700 per year. From the ₹5 lakh annual premium considered earlier, this leaves ₹4,73,300 available for investment.
For illustration, assume this amount is invested in an equity mutual fund.
| Pure Term Life Insurance Policy | |
| Sum Assured | ₹ 50,00,000 |
| Policy Term | 30 years |
| Premium Paying Term | 10 years |
| Annualised Premium | ₹ 26,700 |
| Investment | ₹ 4,73,300 |
Based on the assumed investment return, the equity mutual fund grows to a pre-tax maturity value of ₹268 crore.
After considering the applicable capital gains tax, the estimated post-tax value is ₹235 crore. The resulting post-tax IRR is approximately 11.63%.
| Term insurance + Equity Mutual Fund | |||
| Age | Year | Term Insurance premium + Equity Mutual Fund | Death benefit |
| 40 | 1 | -5,00,000 | 50,00,000 |
| 41 | 2 | -5,00,000 | 50,00,000 |
| 42 | 3 | -5,00,000 | 50,00,000 |
| 43 | 4 | -5,00,000 | 50,00,000 |
| 44 | 5 | -5,00,000 | 50,00,000 |
| 45 | 6 | -5,00,000 | 50,00,000 |
| 46 | 7 | -5,00,000 | 50,00,000 |
| 47 | 8 | -5,00,000 | 50,00,000 |
| 48 | 9 | -5,00,000 | 50,00,000 |
| 49 | 10 | -5,00,000 | 50,00,000 |
| 50 | 11 | 0 | 50,00,000 |
| 51 | 12 | 0 | 50,00,000 |
| 52 | 13 | 0 | 50,00,000 |
| 53 | 14 | 0 | 50,00,000 |
| 54 | 15 | 0 | 50,00,000 |
| 55 | 16 | 0 | 50,00,000 |
| 56 | 17 | 0 | 50,00,000 |
| 57 | 18 | 0 | 50,00,000 |
| 58 | 19 | 0 | 50,00,000 |
| 59 | 20 | 0 | 50,00,000 |
| 60 | 21 | 0 | 50,00,000 |
| 61 | 22 | 0 | 50,00,000 |
| 62 | 23 | 0 | 50,00,000 |
| 63 | 24 | 0 | 50,00,000 |
| 64 | 25 | 0 | 50,00,000 |
| 65 | 26 | 0 | 50,00,000 |
| 66 | 27 | 0 | 50,00,000 |
| 67 | 28 | 0 | 50,00,000 |
| 68 | 29 | 0 | 50,00,000 |
| 69 | 30 | 0 | 50,00,000 |
| 70 | 31 | 0 | 50,00,000 |
| 71 | 32 | 0 | 50,00,000 |
| 72 | 33 | 0 | 50,00,000 |
| 73 | 34 | 0 | 50,00,000 |
| 74 | 35 | 0 | 50,00,000 |
| 75 | 36 | 0 | 50,00,000 |
| 76 | 37 | 0 | 50,00,000 |
| 77 | 38 | 0 | 50,00,000 |
| 78 | 39 | 0 | 50,00,000 |
| 79 | 40 | 0 | 50,00,000 |
| 80 | 41 | 0 | 50,00,000 |
| 81 | 42 | 0 | 50,00,000 |
| 82 | 43 | 0 | 50,00,000 |
| 83 | 44 | 0 | 50,00,000 |
| 84 | 45 | 0 | 50,00,000 |
| 85 | 46 | 0 | 50,00,000 |
| 86 | 47 | 0 | 50,00,000 |
| 87 | 48 | 0 | 50,00,000 |
| 88 | 49 | 0 | 50,00,000 |
| 89 | 50 | 0 | 50,00,000 |
| 90 | 51 | 0 | 50,00,000 |
| 91 | 52 | 0 | 50,00,000 |
| 92 | 53 | 0 | 50,00,000 |
| 93 | 54 | 0 | 50,00,000 |
| 94 | 55 | 0 | 50,00,000 |
| 95 | 56 | 0 | 50,00,000 |
| 96 | 57 | 0 | 50,00,000 |
| 97 | 58 | 0 | 50,00,000 |
| 98 | 59 | 0 | 50,00,000 |
| 99 | 60 | 0 | 50,00,000 |
| 2,35,29,98,369 | |||
| IRR | 11.63% | ||
| Equity Mutual Fund Tax Calculation | |
| Maturity value after 60 years | 2,68,84,46,994 |
| Purchase price | 47,33,000 |
| Long-Term Capital Gains | 2,68,37,13,994 |
| Exemption limit | 1,25,000 |
| Taxable LTCG | 2,68,35,88,994 |
| Tax paid on LTCG | 33,54,48,624 |
| Maturity value after tax | 2,35,29,98,369 |
The comparison highlights the potential impact of keeping insurance costs separate from the investment portfolio.
The mutual fund investment is exposed to market risk, but the investor retains greater control over the investment, including the choice of fund, asset allocation, and when to redeem the investment.
For consistency, the comparison assumes that the mutual fund is redeemed at age 99, matching the maturity point used for the Bajaj Life Supreme Horizon illustration. However, unlike the insurance policy’s predetermined maturity structure, mutual funds generally offer greater liquidity, allowing investors to redeem their investments when required, subject to applicable exit loads and tax rules.
The comparison therefore highlights a significant difference between the two approaches: the Bajaj Life Supreme Horizon illustration produces a substantially lower investor IRR than the separate term insurance + equity mutual fund illustration, despite both involving market-linked investment exposure.
When evaluating a long-term wealth-creation product, investors should therefore look beyond the projected maturity value and compare the actual IRR, costs, liquidity, insurance adequacy, and flexibility of the alternatives.
Final Verdict on the Bajaj Life Supreme Horizon
Bajaj Life Supreme Horizon is a Unit-Linked Insurance Plan (ULIP) that combines life insurance with market-linked investments.
However, the plan involves multiple charges that can reduce the amount available for investment and, consequently, the investor’s long-term returns.
While some charges may be returned later, this does not fully offset the impact of having less money invested during the intervening period. The time value of money is an important consideration that should not be overlooked.
The benefit illustration further highlights the gap between the assumed fund returns and the returns ultimately received by the investor.
Despite equity-market exposure, the illustrated IRRs are considerably lower than the corresponding assumed investment rates and it also has a high agent commission.
Over a long investment horizon, such a difference can have a substantial impact on wealth creation and the ability to meet inflation-adjusted financial goals.
A useful alternative is to evaluate insurance and investment separately. For life protection, a pure term insurance policy can provide the required cover at a relatively lower cost.
The remaining amount can then be invested in market-linked products such as mutual funds, selected according to the investor’s goals, time horizon, and risk profile.
The key takeaway is to evaluate a product based not merely on its projected maturity value or headline features, but on its net returns, charges, liquidity, risk, and adequacy of insurance cover.
Do Quora, Facebook, and Twitter have the final say when it comes to financial advice?
Before investing, compare the product with suitable alternatives and consider whether its overall structure is aligned with your financial goals.
Leave a Comment